Budget apps are genuinely useful — they categorize transactions, track totals, and generate tidy charts that make you feel like you have a handle on things. But there's a gap between what the algorithm sees and what's actually driving your spending, and that gap tends to stay invisible unless you're writing things down by hand. A short monthly spending diary, kept separately from YNAB or Mint or whatever app you rely on, has a way of surfacing the emotional and contextual patterns that automated tools simply aren't built to notice.
Write It Down the Old Way, Even Briefly
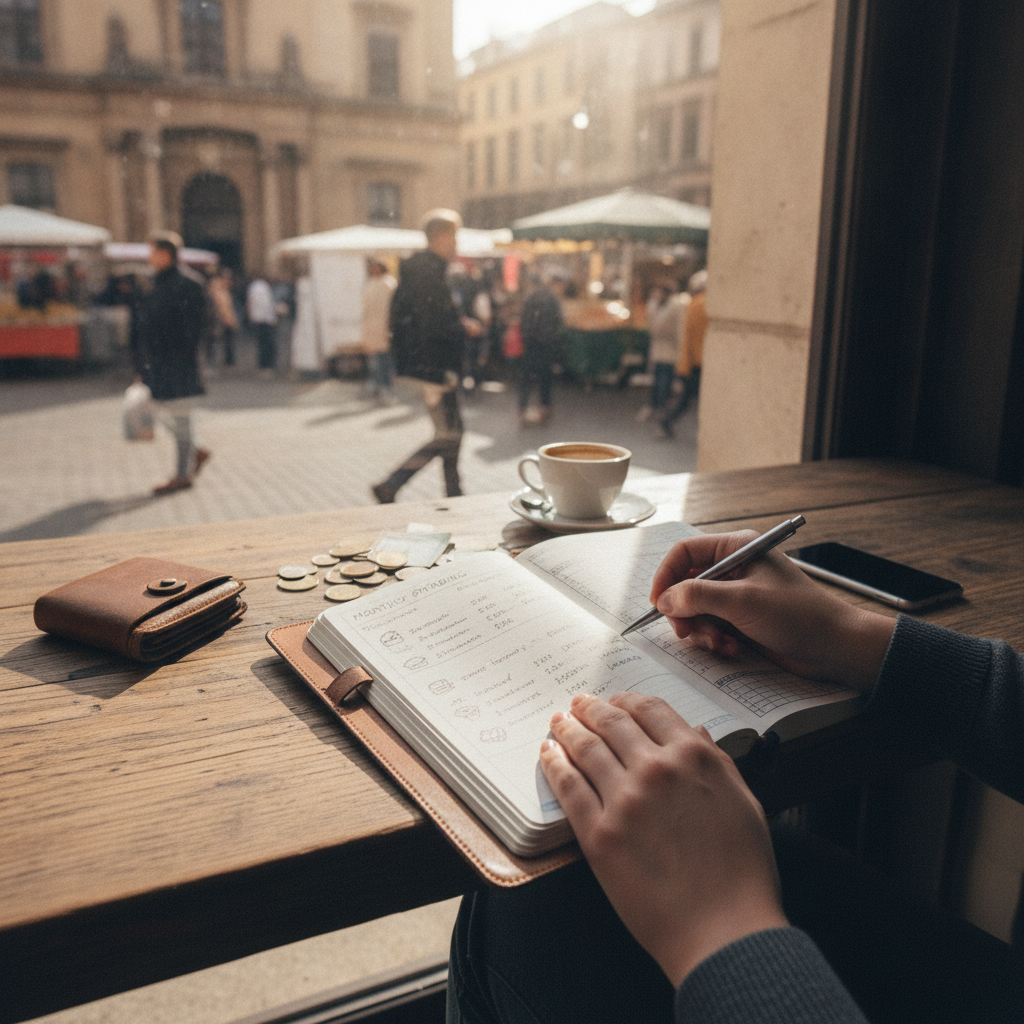
You don't need a leather-bound journal or a complex system. A plain notebook, a cheap spiral pad, or even a notes app you use manually — the key is that you're entering the information yourself, deliberately, rather than having it pulled from your bank feed. The act of writing it down forces a brief moment of reflection that importing data never requires. Even five minutes at the end of each week is enough to start building a clearer picture of where your money is actually going and, more importantly, why.
Note the Context, Not Just the Category
Your budget app might log a coffee shop charge under "Dining" and leave it there. Your diary can go further: you had three coffees this week because Tuesday's meeting ran long, Wednesday felt like a reset after a stressful morning, and Thursday was just habit. Context matters enormously when you're trying to understand patterns. When you can see that certain spending consistently follows stress, boredom, or social pressure, you're working with information no algorithm is set up to gather on your behalf.
Flag Purchases That Felt Automatic
One of the most useful diary habits is marking any purchase you made without really thinking about it. Not impulsive in a dramatic way — just automatic. The streaming service you forgot you still subscribe to, the snack you grabbed at the checkout counter, the app upgrade you approved without checking the price. These small, semi-conscious transactions rarely register emotionally, which is exactly why they accumulate unnoticed. Flagging them in your diary creates a simple visual record that a pie chart won't produce.
Track Mood or Energy Alongside Spending
You don't need to get clinical about this — just a word or two next to certain entries is enough. "Tired," "restless," "celebratory," "avoiding work" — these small labels start to reveal connections over time. After two or three months, you'll likely notice that your spending in one or two categories spikes consistently around the same emotional states. Recognizing that connection is genuinely useful, not because it makes you feel guilty, but because it gives you something specific to work with rather than a vague sense that you overspend sometimes.
Review Month-to-Month Rather Than Day-to-Day
The temptation with any tracking habit is to check it too often. Daily reviews of a spending diary tend to produce anxiety rather than insight, because one day doesn't tell you much on its own. Monthly reviews, by contrast, give you enough distance to spot actual patterns rather than noise. Set aside twenty minutes at the end of each month — something like the last Sunday — to read back through what you've written. Look for recurring entries, recurring contexts, and recurring emotional states. The patterns become visible at that scale in a way they don't during weekly check-ins.
Compare Your Diary to Your App at the End of Each Month
This is where the real value of keeping both systems comes through. Pull up your budget app summary alongside your handwritten diary and look for discrepancies — not in the numbers, but in the story. Your app might show that you stayed within your dining budget, while your diary reveals that half of those meals were stress-driven rather than social or planned. That distinction matters for how you think about changing your habits going forward. The app confirms what happened; the diary explains why.
Keep It Short Enough to Actually Maintain
The diary only works if you keep it going, and that means keeping it manageable. Three to five lines per entry is plenty. You're not writing a financial memoir — you're leaving yourself breadcrumbs. If you've ever tried and abandoned a detailed budgeting journal, this lighter approach is worth another attempt. The purpose is pattern recognition over time, not exhaustive record-keeping. Apps like Notion or even a basic Google Doc can work if a physical notebook doesn't fit your routine.
The habits around personal finance are evolving in an interesting direction. More people are recognizing that financial wellbeing isn't purely a math problem — it's also a behavioral and emotional one. Tools will continue to improve at tracking what you spend, but the reflective work of understanding the context behind those choices remains deeply personal. A short monthly diary bridges that space simply and without much friction, and over time, the patterns it surfaces tend to be exactly the ones that are worth addressing.